The following is general information, not legal advice. Consult an attorney before taking any action based on it.
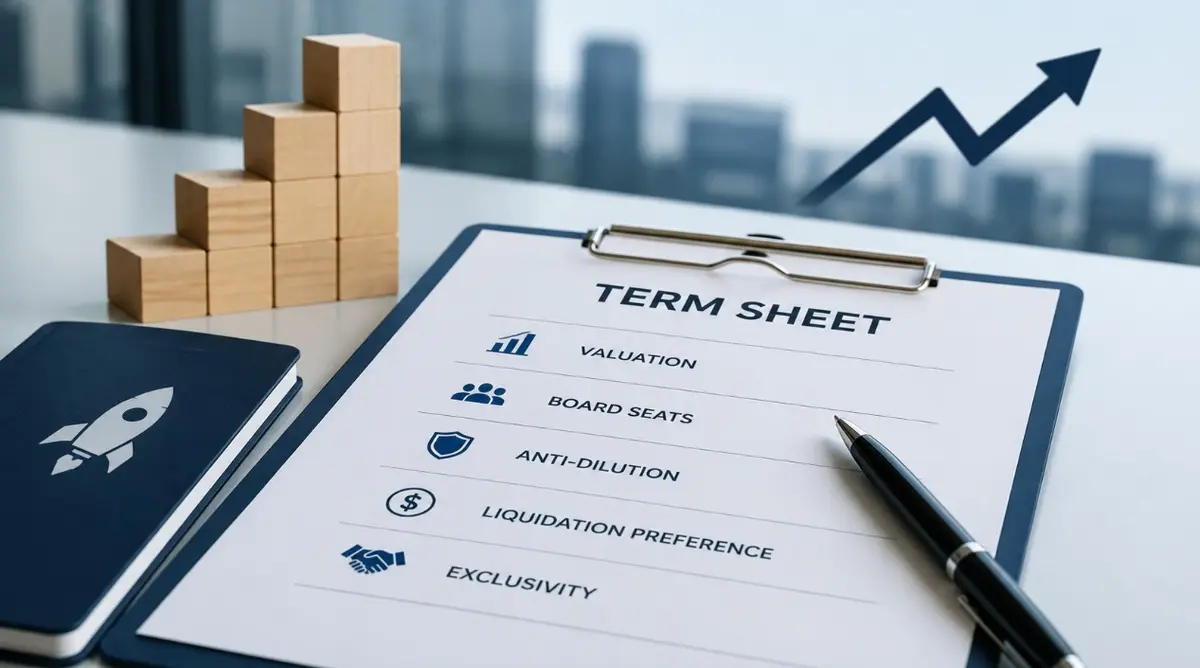
Most founders receiving their first term sheet from a US VC feel overwhelmed by unfamiliar terminology and dense clauses. But a term sheet is a summary of proposed investment terms — and what actually matters isn't understanding every clause, it's knowing which ones are the real negotiation points.
Why the Term Sheet Stage Is Decisive
The term sheet stage matters because a venture relationship doesn't end at closing — investors and the company stay connected through IPO or exit. And once the core terms in a term sheet are signed, they are very difficult to reopen at the definitive-agreement stage. The center of gravity in negotiation sits at the term sheet, not the final contract.
5 Clauses Worth Your Negotiation Effort
1. Valuation & Dilution — the price of the deal. Check specifically whether the option pool is calculated on a pre-money basis, since that materially affects a founder's actual dilution.
2. Board Composition — shapes post-investment decision-making. Early-stage boards commonly run 2 founder seats to 1 investor seat, but the real substance is the scope of matters requiring investor-director consent, not the headcount alone.
3. Protective Provisions — give investors veto rights over things like charter amendments, new share issuances, company sale, and major asset disposals, directly affecting how the company operates. Review carefully what's included and what voting threshold applies.
4. Anti-dilution Protection — present in nearly every US VC deal. The market-standard approach is broad-based weighted average; if a founder-unfriendly full ratchet structure is proposed, it warrants legal review before proceeding.
5. Exclusivity — prevents the company from negotiating with other investors for a set period, and is one of the few legally binding clauses within a term sheet itself. Market practice runs 30–45 days; anything longer is worth pushing back on.
Clauses Already Standardized — Low Negotiation Value
By contrast, liquidation preference (on a 1x non-participating basis), standard dividend clauses, information rights, conversion rights, registration rights, rights of first refusal and co-sale, and typical conditions precedent are already market-standardized, so fighting over each one tends to waste time and money. The efficient approach: identify the terms that matter most to your company first, then quickly confirm the rest align with market practice.
What This Means for Marketing and Growth Leaders
This framework extends well beyond fundraising. Whether it's a contract or a campaign, resources are finite — spending equal energy on every line item scatters focus away from what actually drives outcomes. Distinguishing "what materially affects results" from "what's already standard and not worth debating" is a principle that applies directly to agency contracts, partnership negotiations, and budget allocation.
One more thing worth internalizing: the relationship continues after the deal closes. Just as term-sheet negotiation is about aligning both parties' interests, relationships with partners, platforms, and agencies create more sustainable growth when designed as long-term partnerships rather than one-off transactions. Winning one favorable term today matters less than building a structure built to last.
Need help structuring long-term partnerships that scale with your growth? Best Partner's services can help, or get in touch to talk through your situation.